Marcus, Priya and Rosa's stories showed three times hospital indemnity helped. Here are two times it didn't, and why. The people are made up; the plan rules are real.
Both people have the same plans as those stories: California's Silver plan (you pay the first $4,700, then 30%, up to $11,650 a year) and a sample hospital indemnity plan ($1,000 when admitted, $250 a day, $100 for an observation stay).
Story 4: Jordan's long night
Jordan, 41, went to the ER at midnight with chest pain. The hospital kept him on a monitor and ran tests for about 20 hours. It wasn't his heart.
- His share: a $400 ER fee plus tests and overnight care: about $1,900
- Hospital indemnity paid: $100
Jordan slept in a hospital bed, but he was never officially admitted. He was under observation the whole time, which counts as an outpatient visit.
What if… the doctor had admitted him? He'd have received $1,250. What if he had a different plan? One real plan we reviewed counts 20 hours or more of observation as a hospital stay. Same night, very different payout.
Story 5: Elena's gallbladder
Elena, 46, bought a hospital indemnity plan on her own in January. Last fall, she'd seen her doctor twice for gallbladder pain. In April she was admitted for 2 days for surgery.
- Her share: $4,700 + 30% of $10,300 = $7,790
- Hospital indemnity paid: $0
Her plan had a pre-existing condition rule: for the first 12 months, it didn't pay for health problems treated in the 6 months before she signed up. Her doctor visits fell in that look-back, and her surgery fell in that first year.
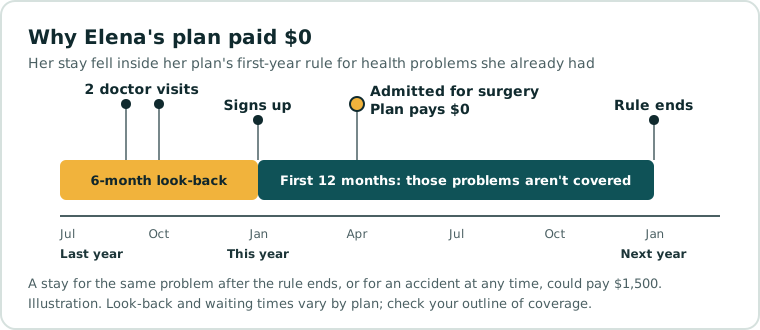
What if… her stay had been for an accident, like a fall? That rule wouldn't apply, and she'd have received $1,500. What if it had happened after next January? The rule would have ended.
All five stories side by side
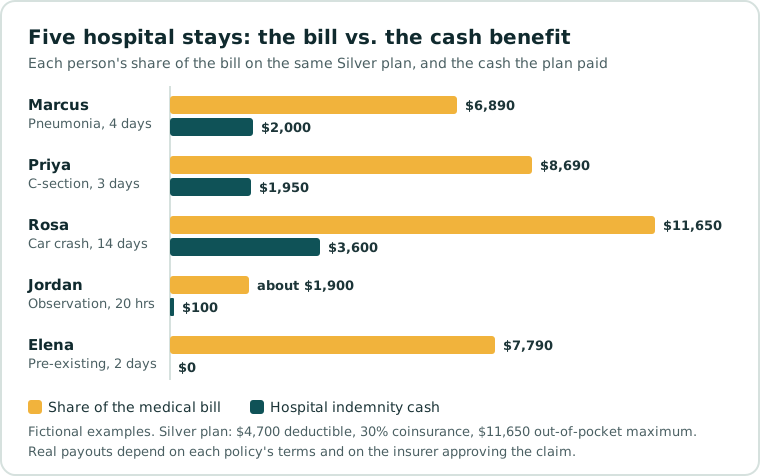
| Person | Their share | Cash paid | Share covered |
|---|---|---|---|
| Marcus, pneumonia | $6,890 | $2,000 | 29% |
| Priya, C-section | $8,690 | $1,950 | 22% |
| Rosa, car crash | $11,650 | $3,600 | 31% |
| Jordan, observation | about $1,900 | $100 | 5% |
| Elena, earlier health problem | $7,790 | $0 | 0% |
How to avoid the surprise
- Ask if you're admitted. If you're kept overnight, ask: "Am I admitted, or here for observation?"
- Read the pre-existing condition rule before you sign up: how far back it looks and how long it lasts.
- Know the list of things it won't pay for, like injuries from drunk driving.
Most surprises come from words people didn't know to look for. A licensed agent or broker in your state can walk you through a plan's definitions, like "admitted" and "pre-existing," before you sign up instead of after a claim.
Your health plan matters too: a Bronze plan leaves a much bigger gap than a Gold plan. See hospital indemnity alongside real ACA plans.
Sources
Hospital indemnity pays only for the events its policy lists; it isn't comprehensive coverage. CMS fact sheet on fixed indemnity coverage.
The observation and pre-existing condition rules come from the outlines of coverage for two employer hospital indemnity plans we reviewed in October 2026; the 6-month look-back is an example. The Silver plan is from Covered California's 2027 standard plan designs. Covered California (PDF).